

A deck can have an exceptional problem statement and still be a no. Here's what actually killed it.

We launched the @1752vc Pitch Deck Analyzer here this morning, and ~100 founders have run their decks through it in just a couple hours. And I love already seeing founders get feedback on exactly what this analyzer was made for.
Pre-seed deck. 28 slides. Graded C. 8 critical issues, 4 quick wins.
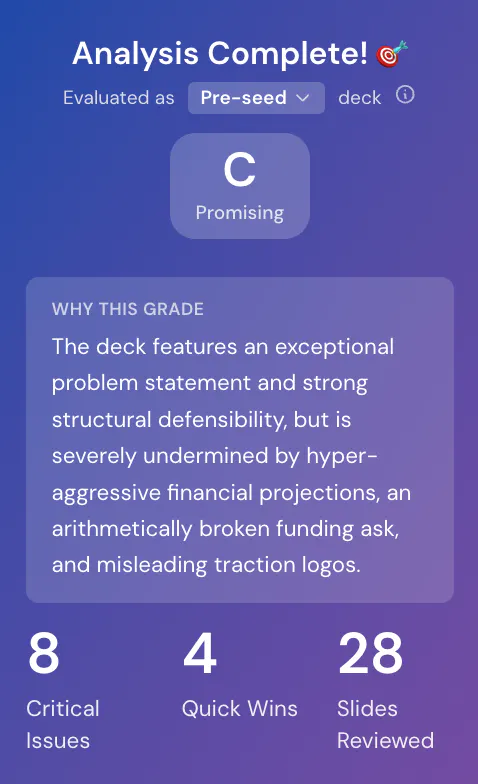
The deck was genuinely good at the thing founders spend all their time on. It died on three things most founders never audit.
1. Projections with nothing underneath them. $210 in current revenue. Raising a $100K pre-seed. Projecting $301M ARR by Year 5. Ambition isn't the problem. The problem is that an investor reads that and concludes you don't know what your own business looks like from the inside.
2. An arithmetically broken ask. The numbers in the ask don't reconcile with each other. That isn't a narrative flaw, it's a math error, and it's one of the first things a partner checks.
3. Misleading traction logos. The quiet one. The moment an investor suspects a logo is doing more work than the relationship behind it, every other claim on the deck becomes suspect too. That's not a deduction, it's the end of the meeting.
None of those are storytelling problems. They're credibility problems. And credibility problems get you a polite no with no explanation attached, because no investor wants to be the one who says "I think you're overstating this."
That's the entire reason we built this. Most decks get passed on and almost none of those founders are ever told why. Not because investors are cruel, but because there's no version of the job where you write thousands of pieces of real feedback a year.
Curious what this community thinks: what's the thing that killed a deck for you that you only found out about long afterwards, if ever?
Replies
the fourth one id add sits between your two and three. the ask reconciles internally and still breaks against the roadmap. eighteen months of runway requested, thirty months of milestones listed two slides later, and nobody on the founding side ever puts those two pages next to each other because they got written weeks apart, usually by different people. on the logos, the thing that finally worked for me was labelling every one with what it actually is. pilot, paid, letter of intent, one conversation. it looks weaker on the slide and it kills the entire class of suspicion you described, because the investor stops having to guess which of the eight are real.